At a Glance
- FlexMoney USA connects borrowers in 22 states with a network of lenders offering online installment, personal, payday, and fast cash loans from $200 up to $35,000, though not every lender offers the top amount.
- FlexMoney is not a lender, so one five-minute form goes to multiple lenders, each of which makes its own credit decision and states its own terms.
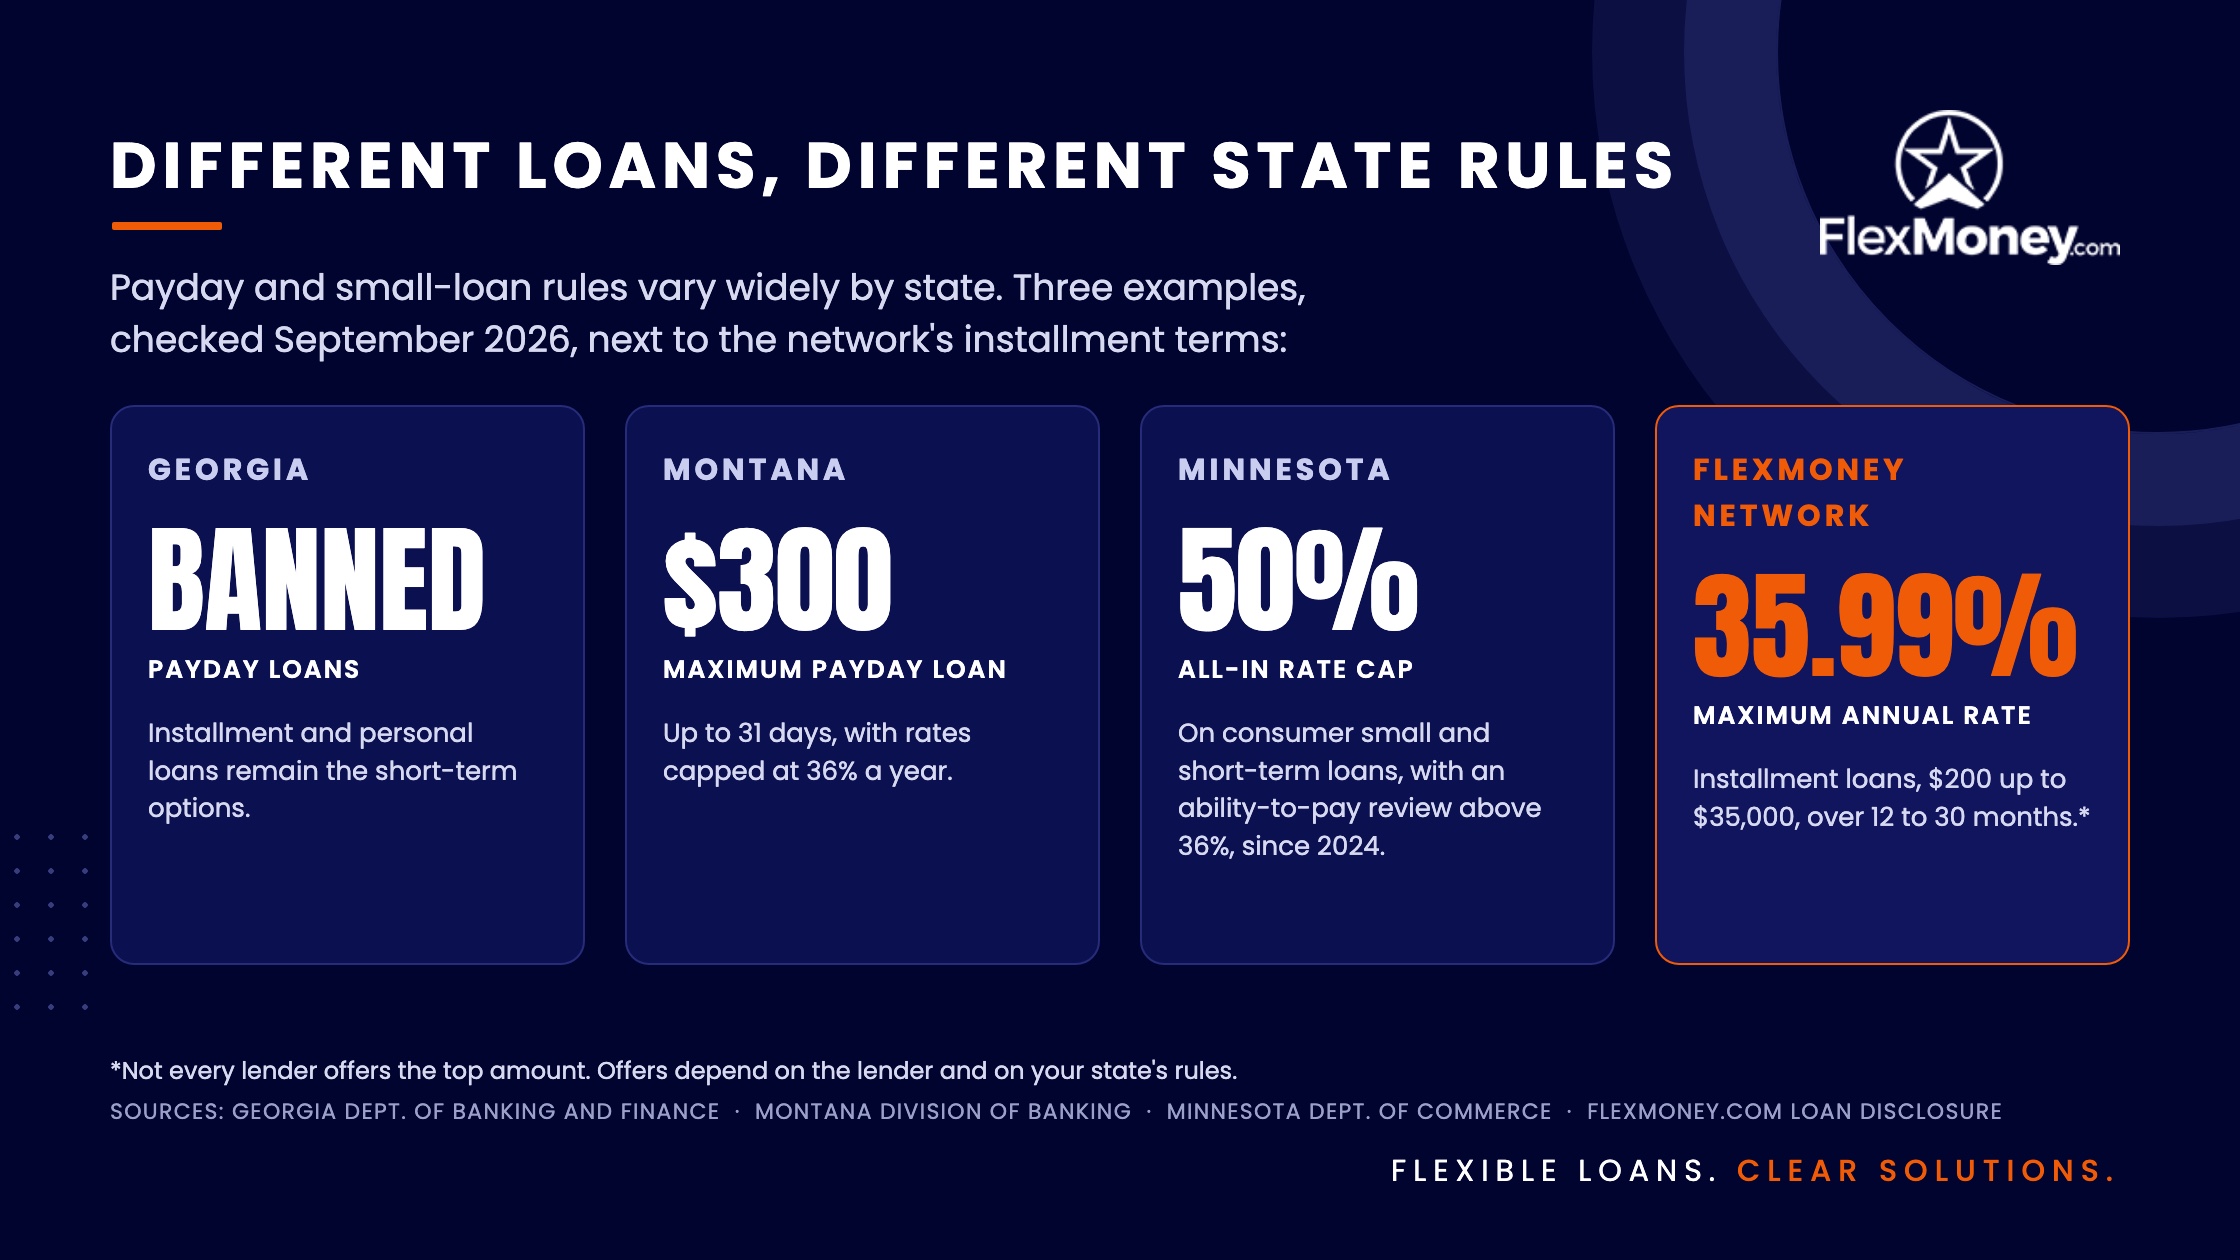
- Every lender in the network caps its annual percentage rate at 35.99%, with repayment plans of 12 to 30 months.
- State law shapes what a short-term loan can look like, from a $300 payday cap in Montana to a 36% rate cap in Colorado and an outright payday ban in Georgia, so what’s available to you depends on your state and on each lender.
- Approved loans can be funded as soon as the next business day, and lenders consider applicants with a range of credit backgrounds, though they may run a credit check.
When dealing with an unexpected financial bump, you can look as an option at an online loan to map out a clear path forward without needing to visit a traditional physical branch. FlexMoney USA serves as an educational and connection gateway across 22 distinct states, allowing consumers to explore how different regional frameworks alter borrowing limits. Instead of navigating separate applications, you can look as an option at a centralized connection network to evaluate what lenders in the network can offer based on your local state laws.
How FlexMoney Connects Borrowers With Lenders
FlexMoney is a loan-matching platform rather than a lender, which means it doesn’t make loans, take applications in its own name, or make credit decisions. When you submit the form, FlexMoney forwards your information to lenders in its network, and any lender interested in your request sends you an offer directly.
That structure has three practical effects for anyone filling out the form. You fill out one form instead of many, which saves an afternoon. Your request is matched with lenders in the network that serve your state. And the terms come from the lender, not from FlexMoney, so the annual percentage rate, the payment, and the term are all spelled out in the offer before you sign anything.
The network’s outer limits are the same in every state: loan amounts from $200 up to $35,000, repayment plans of 12 to 30 months, and a maximum annual percentage rate of 35.99% including interest and fees. Not every lender offers the full $35,000, and the online loans page carries the full disclosure, including a worked example of a $4,300 loan at 35.99% repaid over 30 months at $219.36 a month.
Which States Does FlexMoney Serve?
FlexMoney’s lender network currently serves borrowers in these 22 states. Each state has its own hub page plus dedicated pages for payday, installment, personal, fast cash, and get-money-now loans.
| Region | States served |
| South | Alabama, Georgia, Kentucky, Louisiana, Mississippi, Oklahoma, and Texas are all served. |
| Midwest | Indiana, Kansas, Minnesota, Nebraska, North Dakota, and Ohio are all served. |
| Mountain West | Colorado, Montana, Utah, and Wyoming are all served. |
| West and Northeast | Alaska, Oregon, Washington, New Hampshire, and Rhode Island are all served. |
If your state isn’t listed, the service and its lenders aren’t available there yet, and the section near the end of this guide explains what to do instead.
Why Your State Changes What You Can Borrow
Small-dollar lending is regulated state by state, and the differences are bigger than most borrowers expect. The National Conference of State Legislatures tracks the statutes, and its most recent summary, dated February 2023, shows 37 states with laws that permit payday lending, each with its own cap on the amount, the term, and the fee.
State rules dictate exactly how small-dollar lending functions. For example, Louisiana caps deferred presentment transactions at $740 and small loans at $370 for the year starting September 1, 2026, while Ohio allows short-term loans of up to $1,000 and generally requires a term of at least 91 days unless the monthly payment passes an income test. In a major statutory shift, Minnesota capped consumer small loans and short-term loans at a 50% all-in annual percentage rate and now requires lenders to assess a borrower’s ability to pay on any loan above 36%, for loans made on or after January 1, 2024. Because of these wide regional swings, evaluating an online installment framework through a multi-lender network is a practical way to see what’s on offer where you live. Lenders in the network may also consider steady alternative income, such as long-term disability benefits, structured settlements, and pension distributions, when they evaluate a request.
Installment loans are the common thread across the network, but a 35.99% maximum rate doesn’t by itself settle what’s allowed in any state. Licensing, product definitions, and amount-based limits still apply, so whether a lender makes an offer, and on what terms, depends on the lender and on your state’s rules.
State-by-State Guide to Online Loans Through FlexMoney
The figures below were checked in September 2026 against state statutes and regulators, starting from the National Conference of State Legislatures’ summary. State rules change, so treat these as a starting point and confirm the current law with your lender’s disclosure or your state’s financial regulator. The network’s own limits are the same everywhere: $200 up to $35,000, 12 to 30 months, and an annual percentage rate of 35.99% or lower, subject to each lender and each state’s rules.
The South
- Alabama: Payday options are limited to $500 with a 31-day cap. For larger needs, you can look as an option at an installment loan to give your budget a longer repayment runway.
- Georgia: The state prohibits traditional payday loans entirely. Because of this, personal installment options are the primary short-term paths available for local consumers.
- Kentucky: Payday loans are capped at $600 in total since July 15, 2026, under Senate Bill 219, across no more than two loans, with terms of up to 60 days. Borrowers who need more money or more time can look as an option at an installment loan through the network.
- Louisiana: The Office of Financial Institutions sets the maximum at $740 for deferred presentment transactions and $370 for small loans, from September 1, 2026 to August 31, 2027. Borrowers who need a larger amount or a longer term can compare an installment offer.
- Mississippi: Payday loans are limited to $500 including fees, and the larger transactions must run 28 to 30 days. The per-$100 fees translate to a high annual percentage rate, so compare that cost against an installment offer before choosing.
- Oklahoma: No new payday (deferred deposit) loans have been allowed since August 1, 2020, when the Oklahoma Small Lenders Act replaced them with small installment loans. Installment offers are the product to compare in Oklahoma.
- Texas: Texas lets credit access businesses arrange payday and title loans, and they can charge their own fees on top of the lender’s interest. Compare the total cost in writing before choosing between a payday and an installment offer.
The Midwest
- Indiana: The state’s small loan rules allow up to $825 in total, limited to 20% of gross monthly income, with a minimum 14-day term. Borrowers with larger needs can look as an option at an installment loan.
- Kansas: Payday loans are limited to $500 for 7 to 30 days. Installment loans are the practical choice for anything you can’t repay within a month.
- Minnesota: Consumer small loans are limited to $350, and since January 1, 2024, the all-in annual percentage rate is capped at 50%, with an ability-to-pay review required above 36%. The network’s 35.99% maximum sits below that 36% threshold.
- Nebraska: Payday loans are limited to $500 including fees, for up to 34 days, and the state prohibits any annual percentage rate above 36%. The network’s 35.99% maximum sits below that cap.
- North Dakota: Payday loans are limited to $500, with a total of 60 days including one renewal. Installment loans give North Dakota borrowers a fixed schedule instead of a renewal.
- Ohio: Short-term loans go up to $1,000 with interest capped at 28% a year, and the term must be at least 91 days unless the monthly payment stays within 6% of gross or 7% of net monthly income, whichever is greater, under Ohio law. That rule already pushes short-term lending toward installment structures.
The Mountain West
- Colorado: Payday loans up to $500 require a minimum six-month term, and the annual percentage rate is capped at 36%. The network’s 35.99% maximum sits below that cap.
- Montana: Payday loans are limited to $300 for up to 31 days, with rates capped at 36% a year. Borrowers with larger expenses can look as an option at an installment loan.
- Utah: The state bars rolling a payday loan over beyond 10 weeks from the date it was first made. An installment offer gives Utah borrowers a fixed repayment schedule from the start.
- Wyoming: One-month post-dated check loans carry finance charges of up to $30 or 20% a month, whichever is greater. That monthly cost is steep on an annual basis, so compare it against an installment offer.
The West and Northeast
- Alaska: Payday loans are limited to $500 outstanding, with a minimum term of 14 days. Borrowers who want to repay over several months can look as an option at installment offers through the network.
- Oregon: Short-term loans run 31 to 60 days with interest capped at 36%. The network’s 35.99% maximum sits below that cap.
- Washington: Payday loans are limited to the lower of $700 or 30% of gross monthly income, usually for up to 45 days. Borrowers who need more than $700 can look as an option at an installment loan.
- New Hampshire: Payday loans are limited to $500 for 7 to 30 days, with the annual percentage rate capped at 36%. The network’s 35.99% maximum sits below that cap.
- Rhode Island: Deferred deposit checks with a face amount of up to $500 remain legal for now, but a 2025 law repeals them on January 1, 2027, after which small loans fall under the state’s existing [tiered monthly
What to Expect From the Matching Process in Any State
The process is identical in all 22 states, and it takes about five minutes to start.
- Profile Mapping: A consumer inputs their baseline criteria, financial details, and state of residence on the FlexMoney online loans page.
- Automated Routing: The network screens those details against lenders in the network that serve that specific state. Lenders may run a credit check through Experian, Equifax, or TransUnion, or an alternative credit check.
- Interactive Review: If a match is found, you receive a transparent offer detailing the annual percentage rate, payment dates, and terms. You can look as an option at these disclosures with zero penalty or obligation.
- Capital Distribution: Following the digital verification of an offer, participating lenders process automated clearinghouse transfers that can reach your bank account as soon as the next business day.
If you’re weighing a payday loan against an installment loan in your state, our guide to payday loans versus installment loans lays out the cost difference, and if you want to strengthen your request before you send it, how to maximize your chances of loan approval covers what lenders actually look at.
What If Your State Isn’t on the List?
FlexMoney’s service and its lenders aren’t available in every state, and submitting a request from an unserved state won’t produce an offer. The list above reflects where the network operates today, and the state footer on every FlexMoney page is kept current as coverage changes.
In the meantime, borrowers in unserved states have two reliable options. Federal credit unions offer payday alternative loans with capped rates to their members, and your state’s financial regulator keeps a list of licensed online lenders that can operate where you live. Both are safer starting points than a search result promising loans with no credit check.
Checking Your State’s Options
Before committing to a short-term financial agreement, it is vital to balance the monthly repayment obligations directly against your upcoming payroll calendar. If you want to check your current regional terms without any upfront commitment, you can look as an option at the FlexMoney state pages to evaluate your immediate network options. Always ensure that the loan amount matches a specific, isolated expense rather than stretching out to cover ongoing monthly bill shortfalls.
FlexMoney.com is a loan-matching platform, not a direct financial lender. Submitting your profile details does not guarantee an approval or an offer. Lenders in the network may perform credit checks, and individual service availability is subject to state-level regulations.
Frequently Asked Questions
What states does FlexMoney offer online loans in?
FlexMoney’s lender network serves 22 states: Alabama, Alaska, Colorado, Georgia, Indiana, Kansas, Kentucky, Louisiana, Minnesota, Mississippi, Montana, Nebraska, New Hampshire, North Dakota, Ohio, Oklahoma, Oregon, Rhode Island, Texas, Utah, Washington, and Wyoming. Each state has a hub page plus dedicated pages for payday, installment, personal, fast cash, and get-money-now loans. Across the network, lenders offer amounts from $200 up to $35,000 with annual percentage rates capped at 35.99%, and what’s available in each state depends on the lender and on state law.
Can I get an online loan in Georgia if payday loans are banned there?
Georgia prohibits payday lending but still allows installment and personal loans from licensed lenders, which are the kinds of loans lenders in the FlexMoney network offer. An installment loan through the network runs 12 to 30 months at an annual percentage rate of 35.99% or lower, with fixed monthly payments and no penalty for paying early. Whether a lender makes an offer, and on what terms, depends on the lender and on Georgia law, and approved loans can fund as soon as the next business day.
Are online loans in Alabama available for bad credit?
Lenders in the FlexMoney network consider applicants with a range of credit backgrounds, including Alabama borrowers with bad credit. Alabama law caps payday loans at $500 for up to 31 days, so borrowers who need more money or more time can look as an option at an installment loan instead. A lower score may mean a higher annual percentage rate within the 35.99% cap and a smaller approved amount, and no lender guarantees approval.
Is FlexMoney a direct lender?
No, FlexMoney is a loan-matching platform that forwards one request to a network of lenders that serve your state, and each lender makes its own credit decision and sets its own terms. That’s a real advantage when you’re comparing offers, because you’re not tied to a single lender’s criteria. The trade-off is that FlexMoney can’t tell you in advance whether you’ll be approved or at what rate, since only the lender knows that.
How fast can I get an online loan in my state?
Lenders in the FlexMoney network can deposit approved funds as soon as the next business day in all 22 states. The exact timing depends on the lender, the time of day you sign, and how quickly your bank posts incoming transfers. Submitting your request early on a business day, with accurate bank and income details, can help avoid delays to a next-business-day deposit.